


New Institutional Report Released
Access our strategic market perspective on necessity-based real estate and private credit fundamentals.
Read Full Report
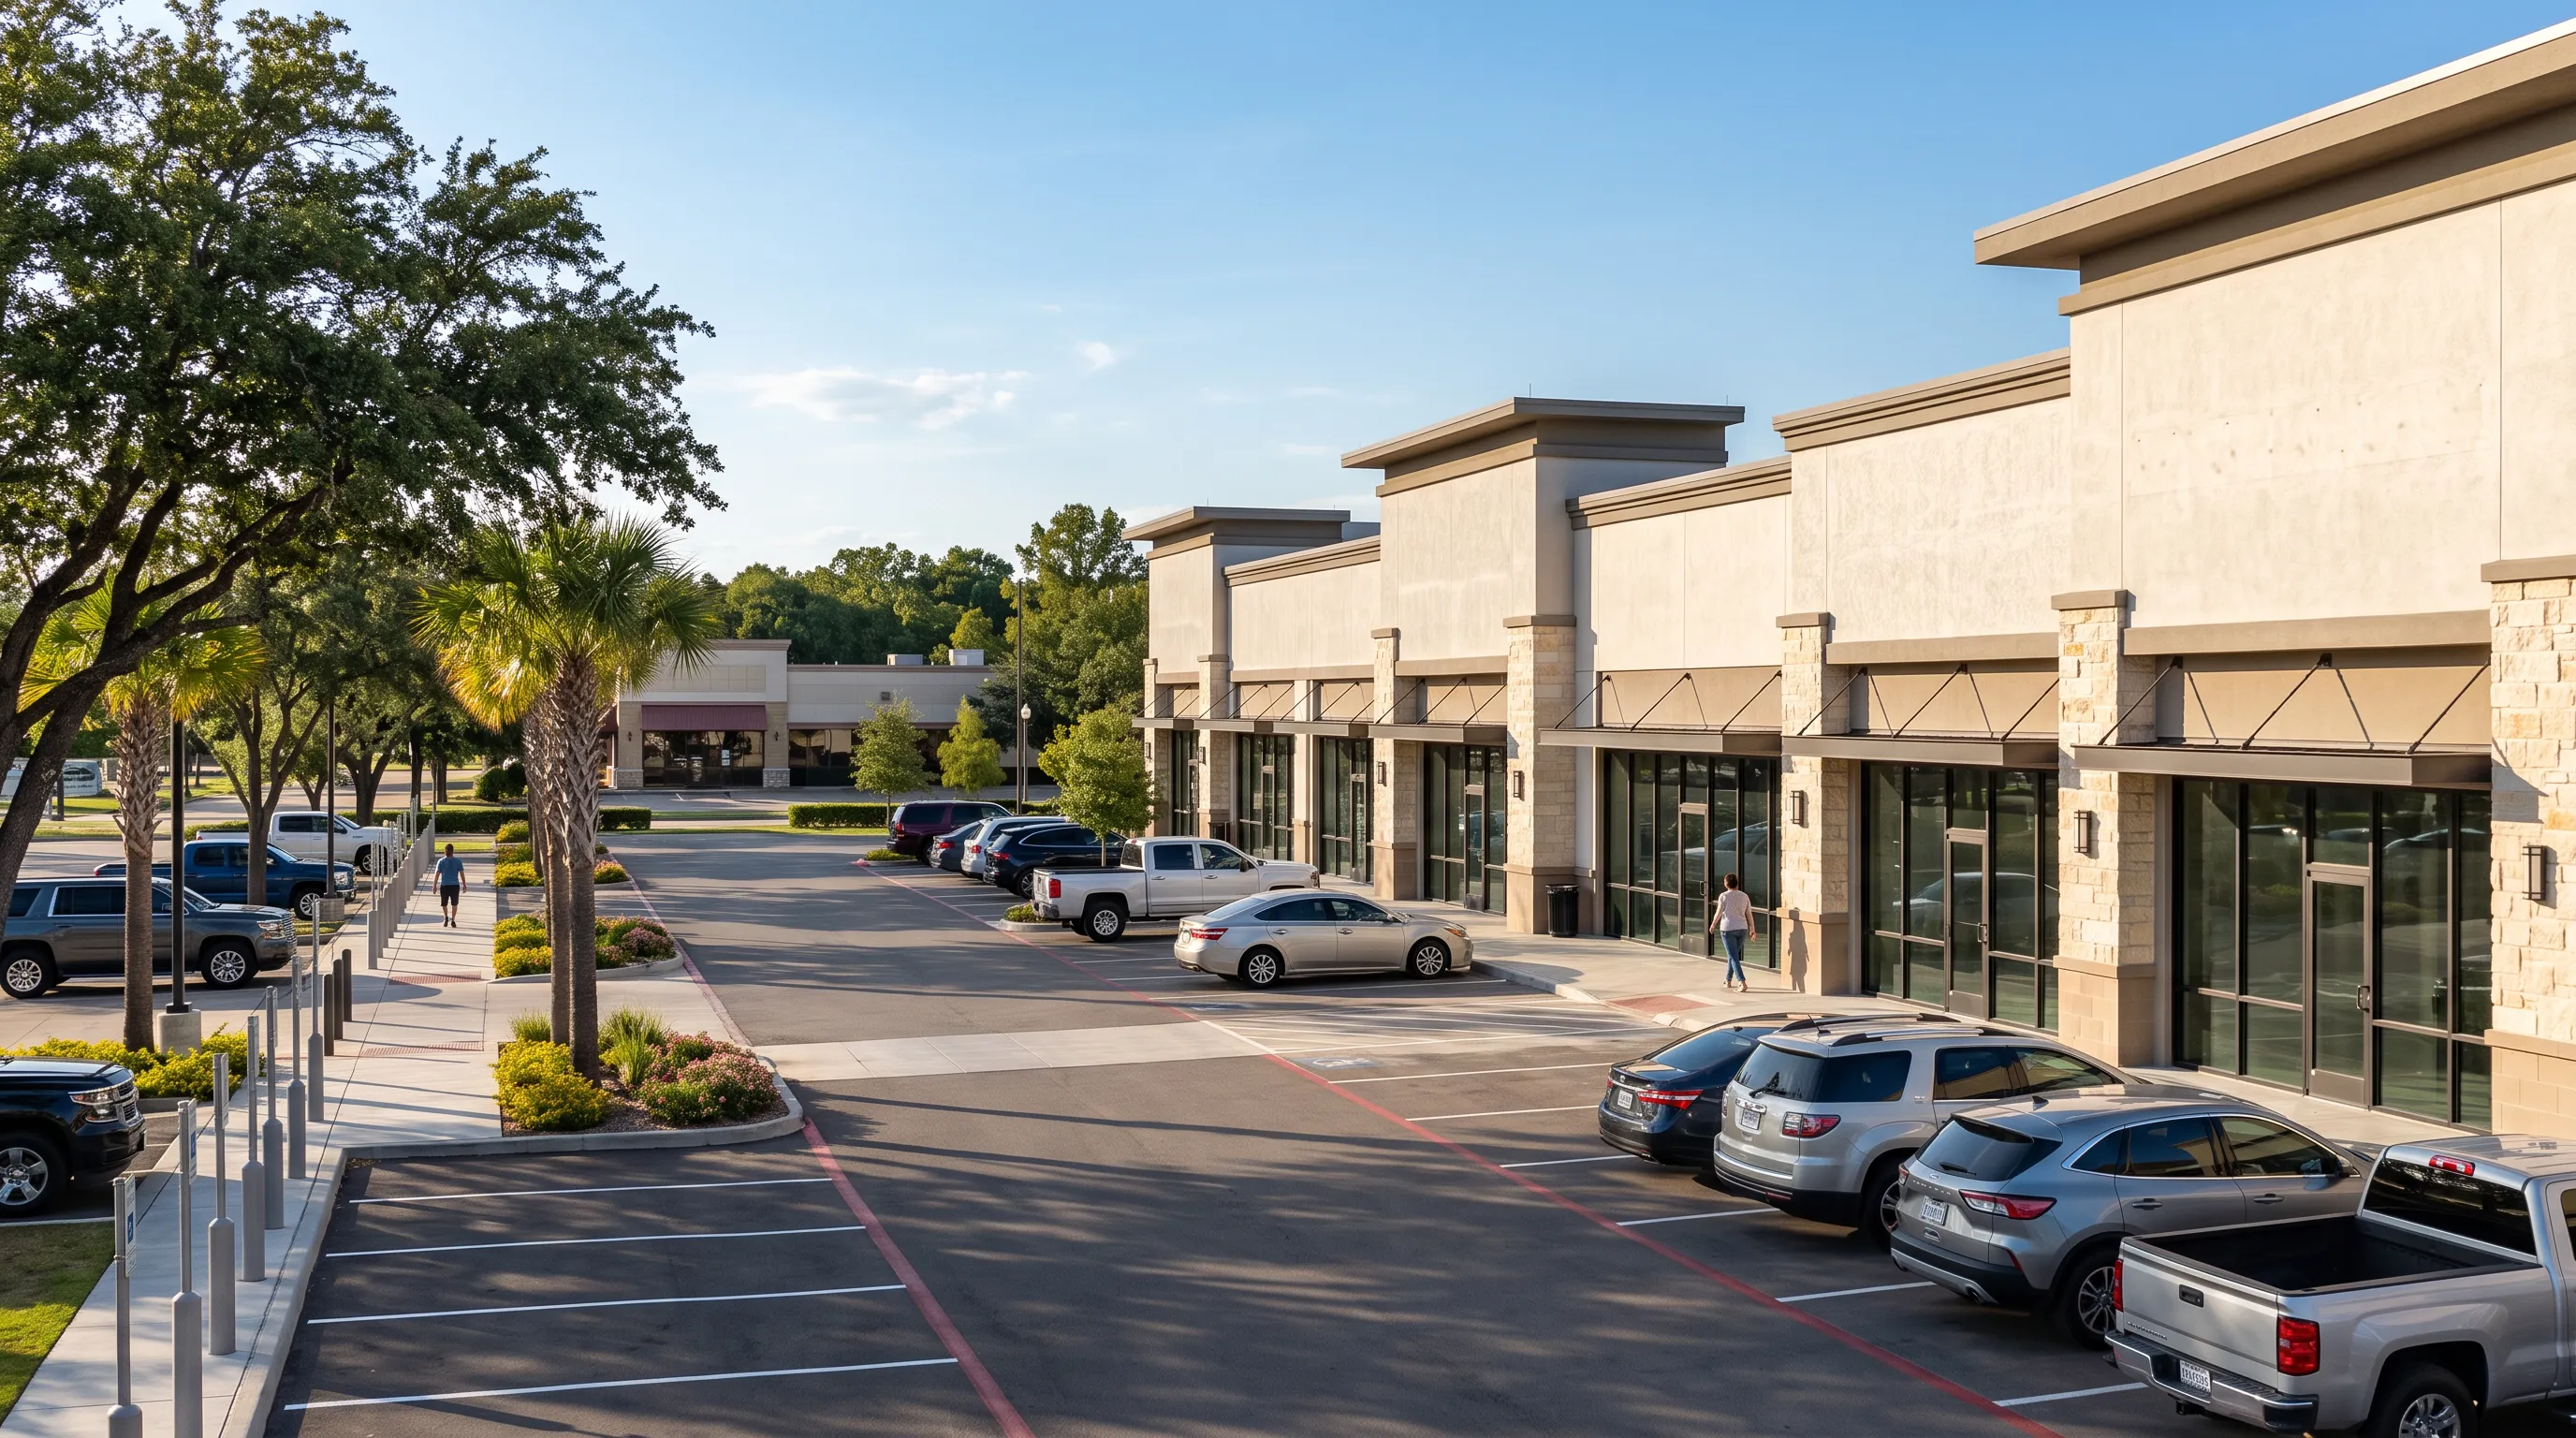
Necessity retail sits at the top of the commercial real estate yield curve and carries the lowest tenant default risk in the business. That contradiction has been true for years. It's 70% of our portfolio because we don't expect it to resolve in the market's favor.
Nobody is having a prescription pickup, a haircut, a dental cleaning, a $1 grocery run or an urgent care visit delivered to their door.
What's left standing is the retail people use on a weekly loop, at a location they can get to in under ten minutes. That's the whole category we buy.
What survives is what people still need.
For fifteen years the market has priced all retail as one asset class in decline. It isn't. Amazon took the parts of retail that ship well - electronics, apparel, books - and left the parts that don't.
Weekly-use retail
The categories that remain are the ones consumers still need locally and repeatedly.
Pricing power
Retail is the only major CRE sector where effective rents exceed asking rents.
Limited supply
Availability is near historic lows and almost nothing is being built.
Pharmacy
7.74% cap rate
Dollar stores
7.34% cap rate
Downtown office
Approximately 4.5–5.5%
We don't buy stabilized, fully-leased, market-rent centers at a market cap rate. That's a bond, and there are cheaper ways to buy a bond. We buy necessity centers with a fixable gap between what they earn today and what they should earn.
Renewals create an immediate opportunity to move income toward market.
Physical issues we can price, improve and translate into better leasing performance.
Strong trade area, viable suites, but insufficient leasing effort.
Recoveries, insurance and operating contracts that can be actively optimized.
Shift discretionary tenancy toward daily-needs and stronger credit.
Situations where execution certainty matters as much as the final price.
Income first. Operational upside second. A clear reason to own the asset from day one.
| CRITERION | OTIMA FOCUS |
|---|---|
Asset Type | Grocery-anchored, service-oriented and daily-needs neighborhood and community centers; select single-tenant net lease in pharmacy, dollar and quick-service formats. |
Anchors | Investment-grade or nationally credited where possible. |
Lease Structure | NNN preferred · 5-15 year terms at entry · CPI or fixed escalators. |
Occupancy at Entry | 75%+ with a specific, costed plan for the remaining vacancy. |
Trade Area | Demonstrable daily-needs demand · positive population and income trends · minimal competing new supply. |
Markets | Texas core · Sun Belt growth corridor with an established local partner. |
Malls · power centers dependent on discretionary spend · unanchored strips with no daily-needs draw · anything where the investment thesis depends on redevelopment rather than income.
Two workstreams run in parallel from day one: the rent roll and the physical asset.
WORKSTREAM 01
Fill vacant suites with an active leasing strategy
Bring expiring leases to market rate
Improve tenant mix toward daily-needs credit
Re-underwrite the operating budget line by line
WORKSTREAM 02
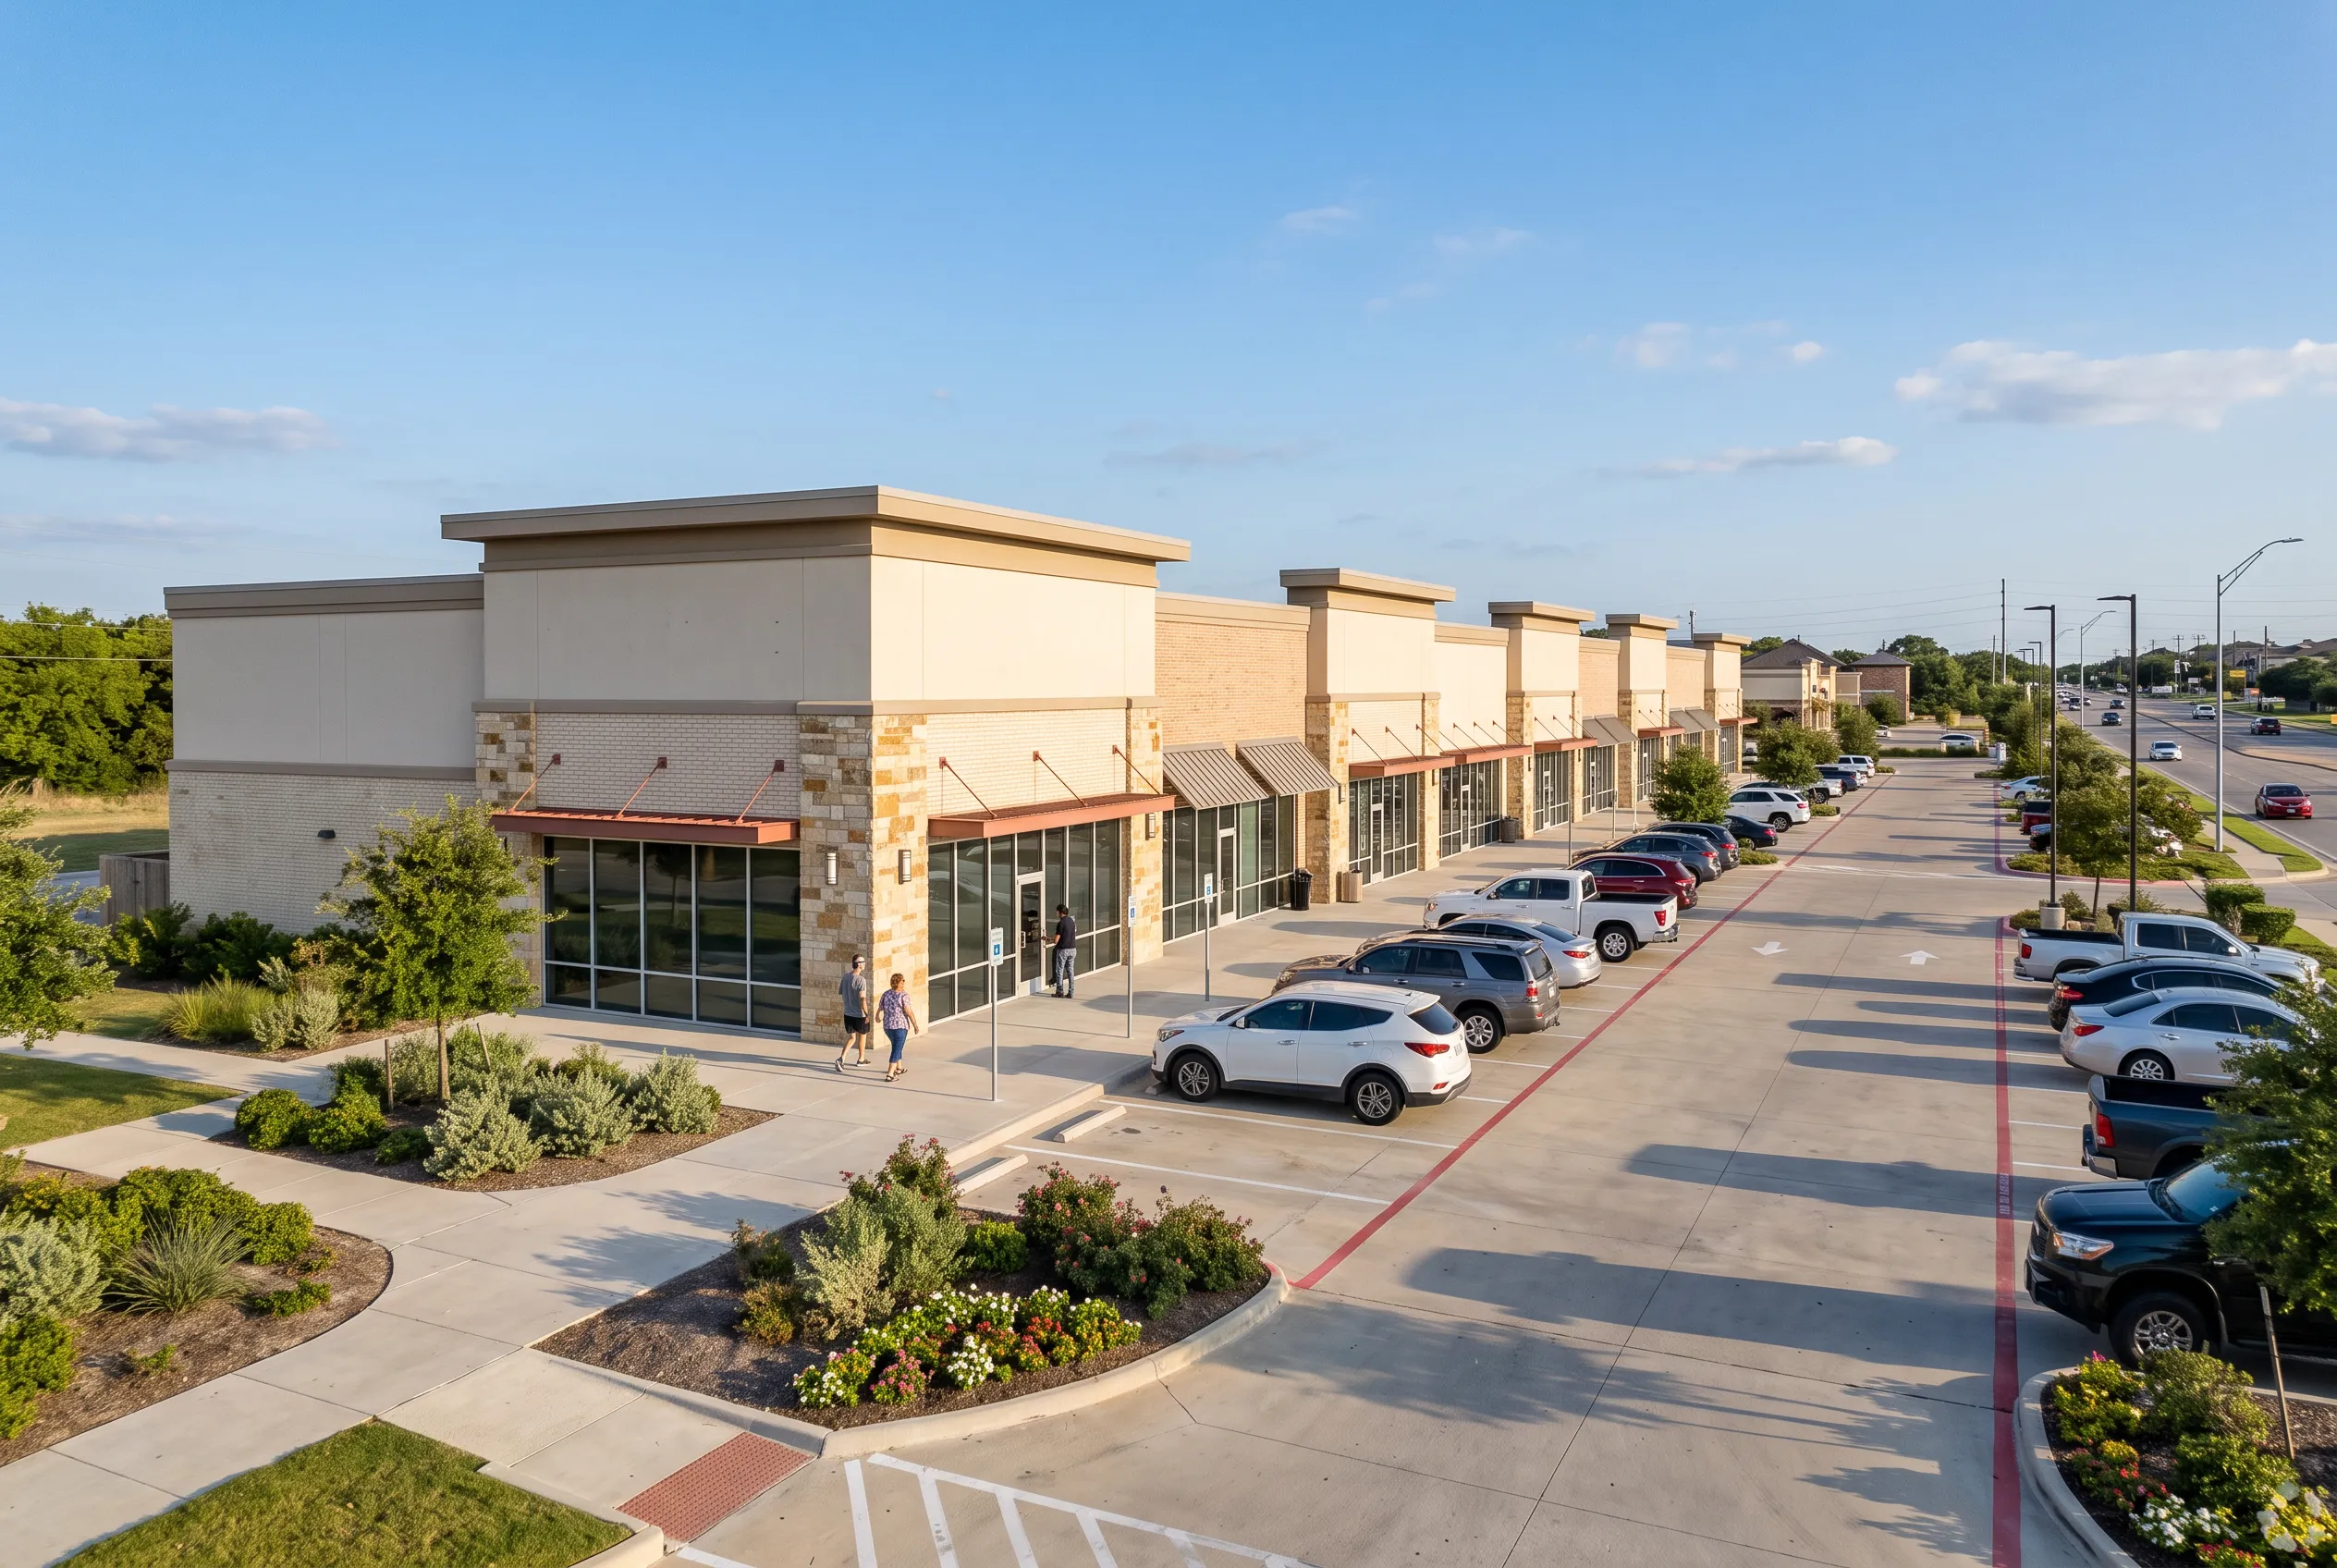
We spend where the dollar comes back in rent, in tenant quality, or in exit value - not on cosmetics for their own sake.
Exterior Paint & Façade Refresh
LED Pylon & Monument Signage
Parking Lot Resurfacing & ADA
LED Site & Canopy Lighting
Landscaping, Planters & Screening
Common-Area & Tenant Upgrades
01 — TYPICAL HOLD
5–7 years
02 — INCOME DURING THE HOLD
Quarterly distributions throughout.
03 — EXIT OPTIONS
Refinance · Individual sale · Portfolio sale · 1031 exchange
04 — PRINCIPLE
No forced timeline. We exit when the market rewards it.
Send it. We'll give you a straight answer, with our reasoning, in days — not a maybe that goes quiet.
Our portfolio runs 70% retail, 20% healthcare, 10% multifamily - not a house view we defend in meetings, just where the risk-adjusted income is right now.
Top of the CRE yield curve, lowest tenant default risk in the business. The market prices a pharmacy like a risk and an office tower like a blue chip. We built the portfolio on that disagreement.
The demographic trade. Demand you can see a decade out, and no way to build enough of it.
Smallest position on purpose. Lower going-in yield, but it reprices every twelve months, so it keeps up when inflation does.
U.S. commercial real estate corrected more than 15% from its 2023 peak and has now posted four consecutive quarters of positive total returns.
A 5-cap in 2022 clears at a 7-cap today - same tenant, same rent, materially less money.
$1T+
U.S. CRE debt matures in 2026-27
Most of that debt will be extended, but enough reaches the market to create real conversations with sellers who need certainty more than the last dollar.
New Supply Stopped
Construction starts across Retail, Healthcare and Multifamily have fallen sharply.
Whatever demand arrives increasingly meets a fixed building stock.
That is what protects rents.
Most of what determines a real estate return happens after the closing table. We staff for that.
Strategic JVs and direct off-market. Fifteen-plus years of relationships means deals reach us before a listing does. ~200 screened a year.
30+ operational and market data points, underwritten across the full cycle and stressed downside-first: anchor leaves, rates stay high, lease-up takes twice as long. If it still works, we're interested.
Three to five high-conviction deals a year, financing locked before we bid. When we commit, we close.
Rebrand, reposition, re-tenant, re-lease. We manage our own assets. Occupancy up, expenses down, NOI up.
Refinance, sell, 1031, or hold. No forced exits. Quarterly distributions while we work.
OTIMA principals co-invest in every deal, on the same terms. Investors are paid first, and our fees are performance-linked - we do well when the asset does, not when it merely closes.
You deal with principals directly, and you get the bad news as fast as the good news. That's not a service promise; it's how a firm this size should work.
*Track Record & Prior Investment Experience: Information regarding prior investments, acquisitions, dispositions, distributions, operating results, or performance-related metrics is provided solely to describe the historical experience of OTIMA, its principals, and/or affiliates in specific prior transactions. A principal's involvement in a prior transaction may have been in a capacity different from their role in future OTIMA-sponsored investments. Past performance is not indicative of and does not guarantee future results. All investments involve risk, including the possible loss of principal. Prospective investors should not rely on prior results as a prediction or guarantee of future performance.Read full disclosure →
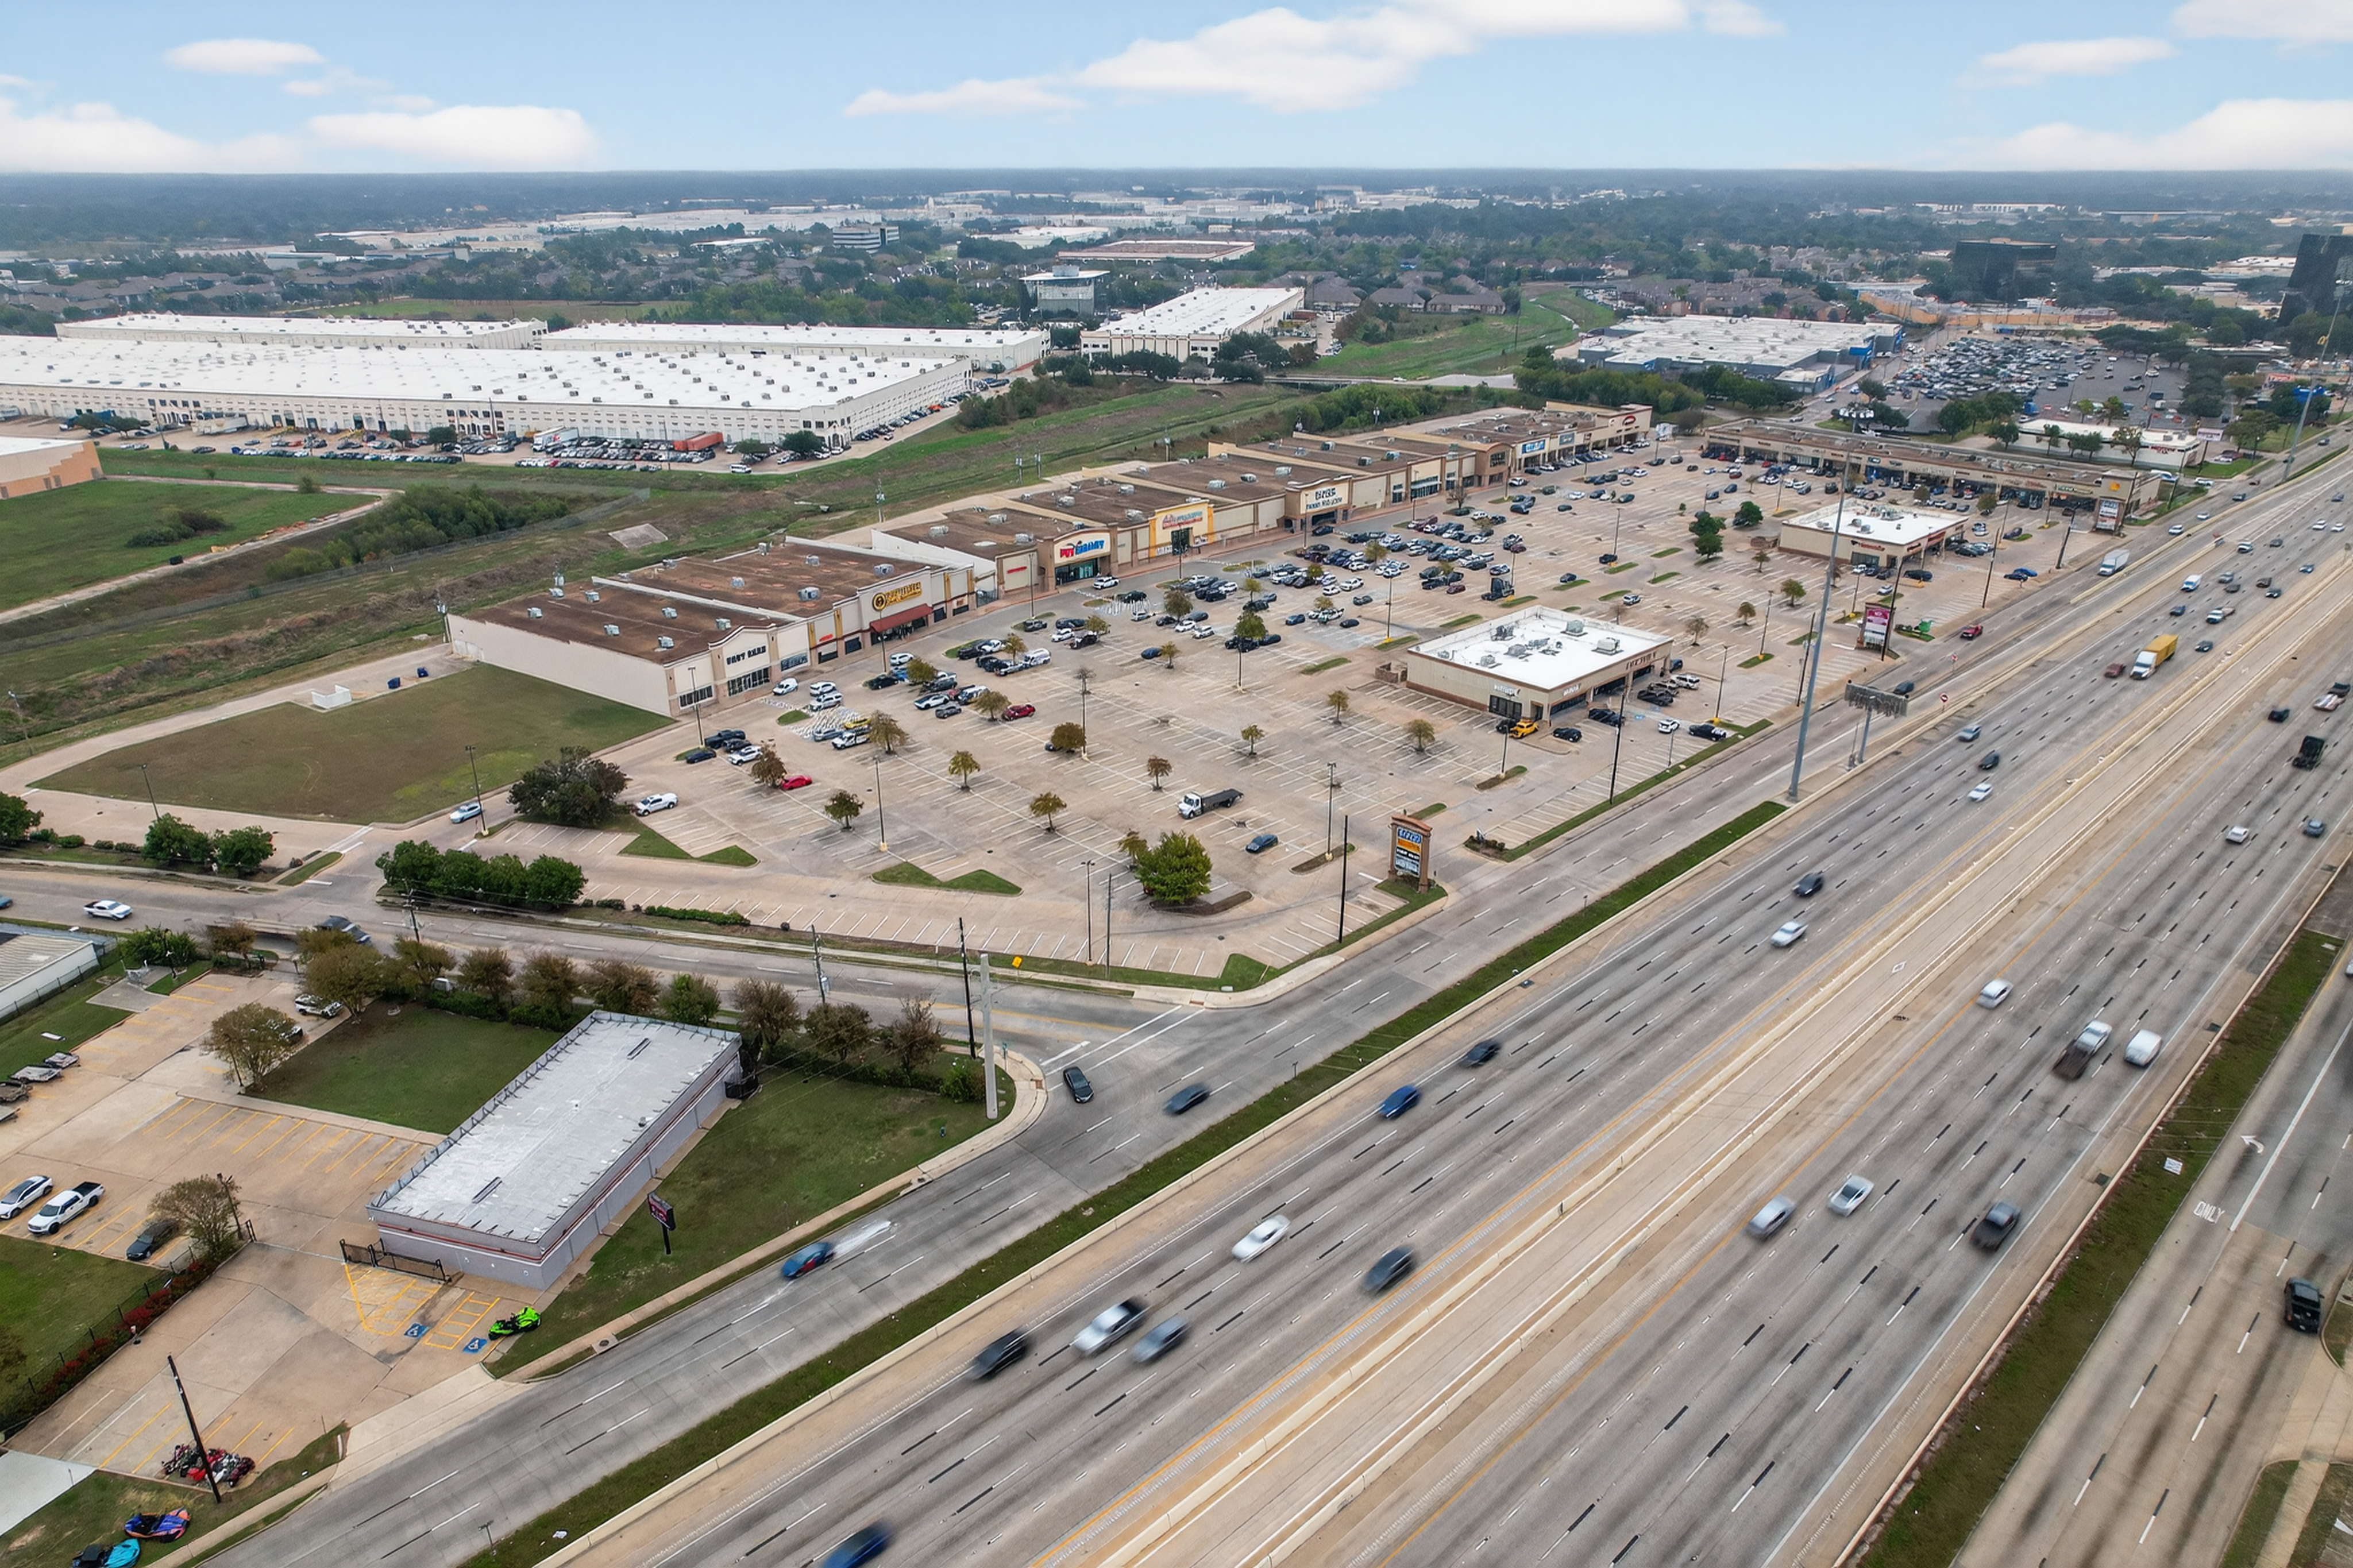
Houston, TX · Necessity Retail
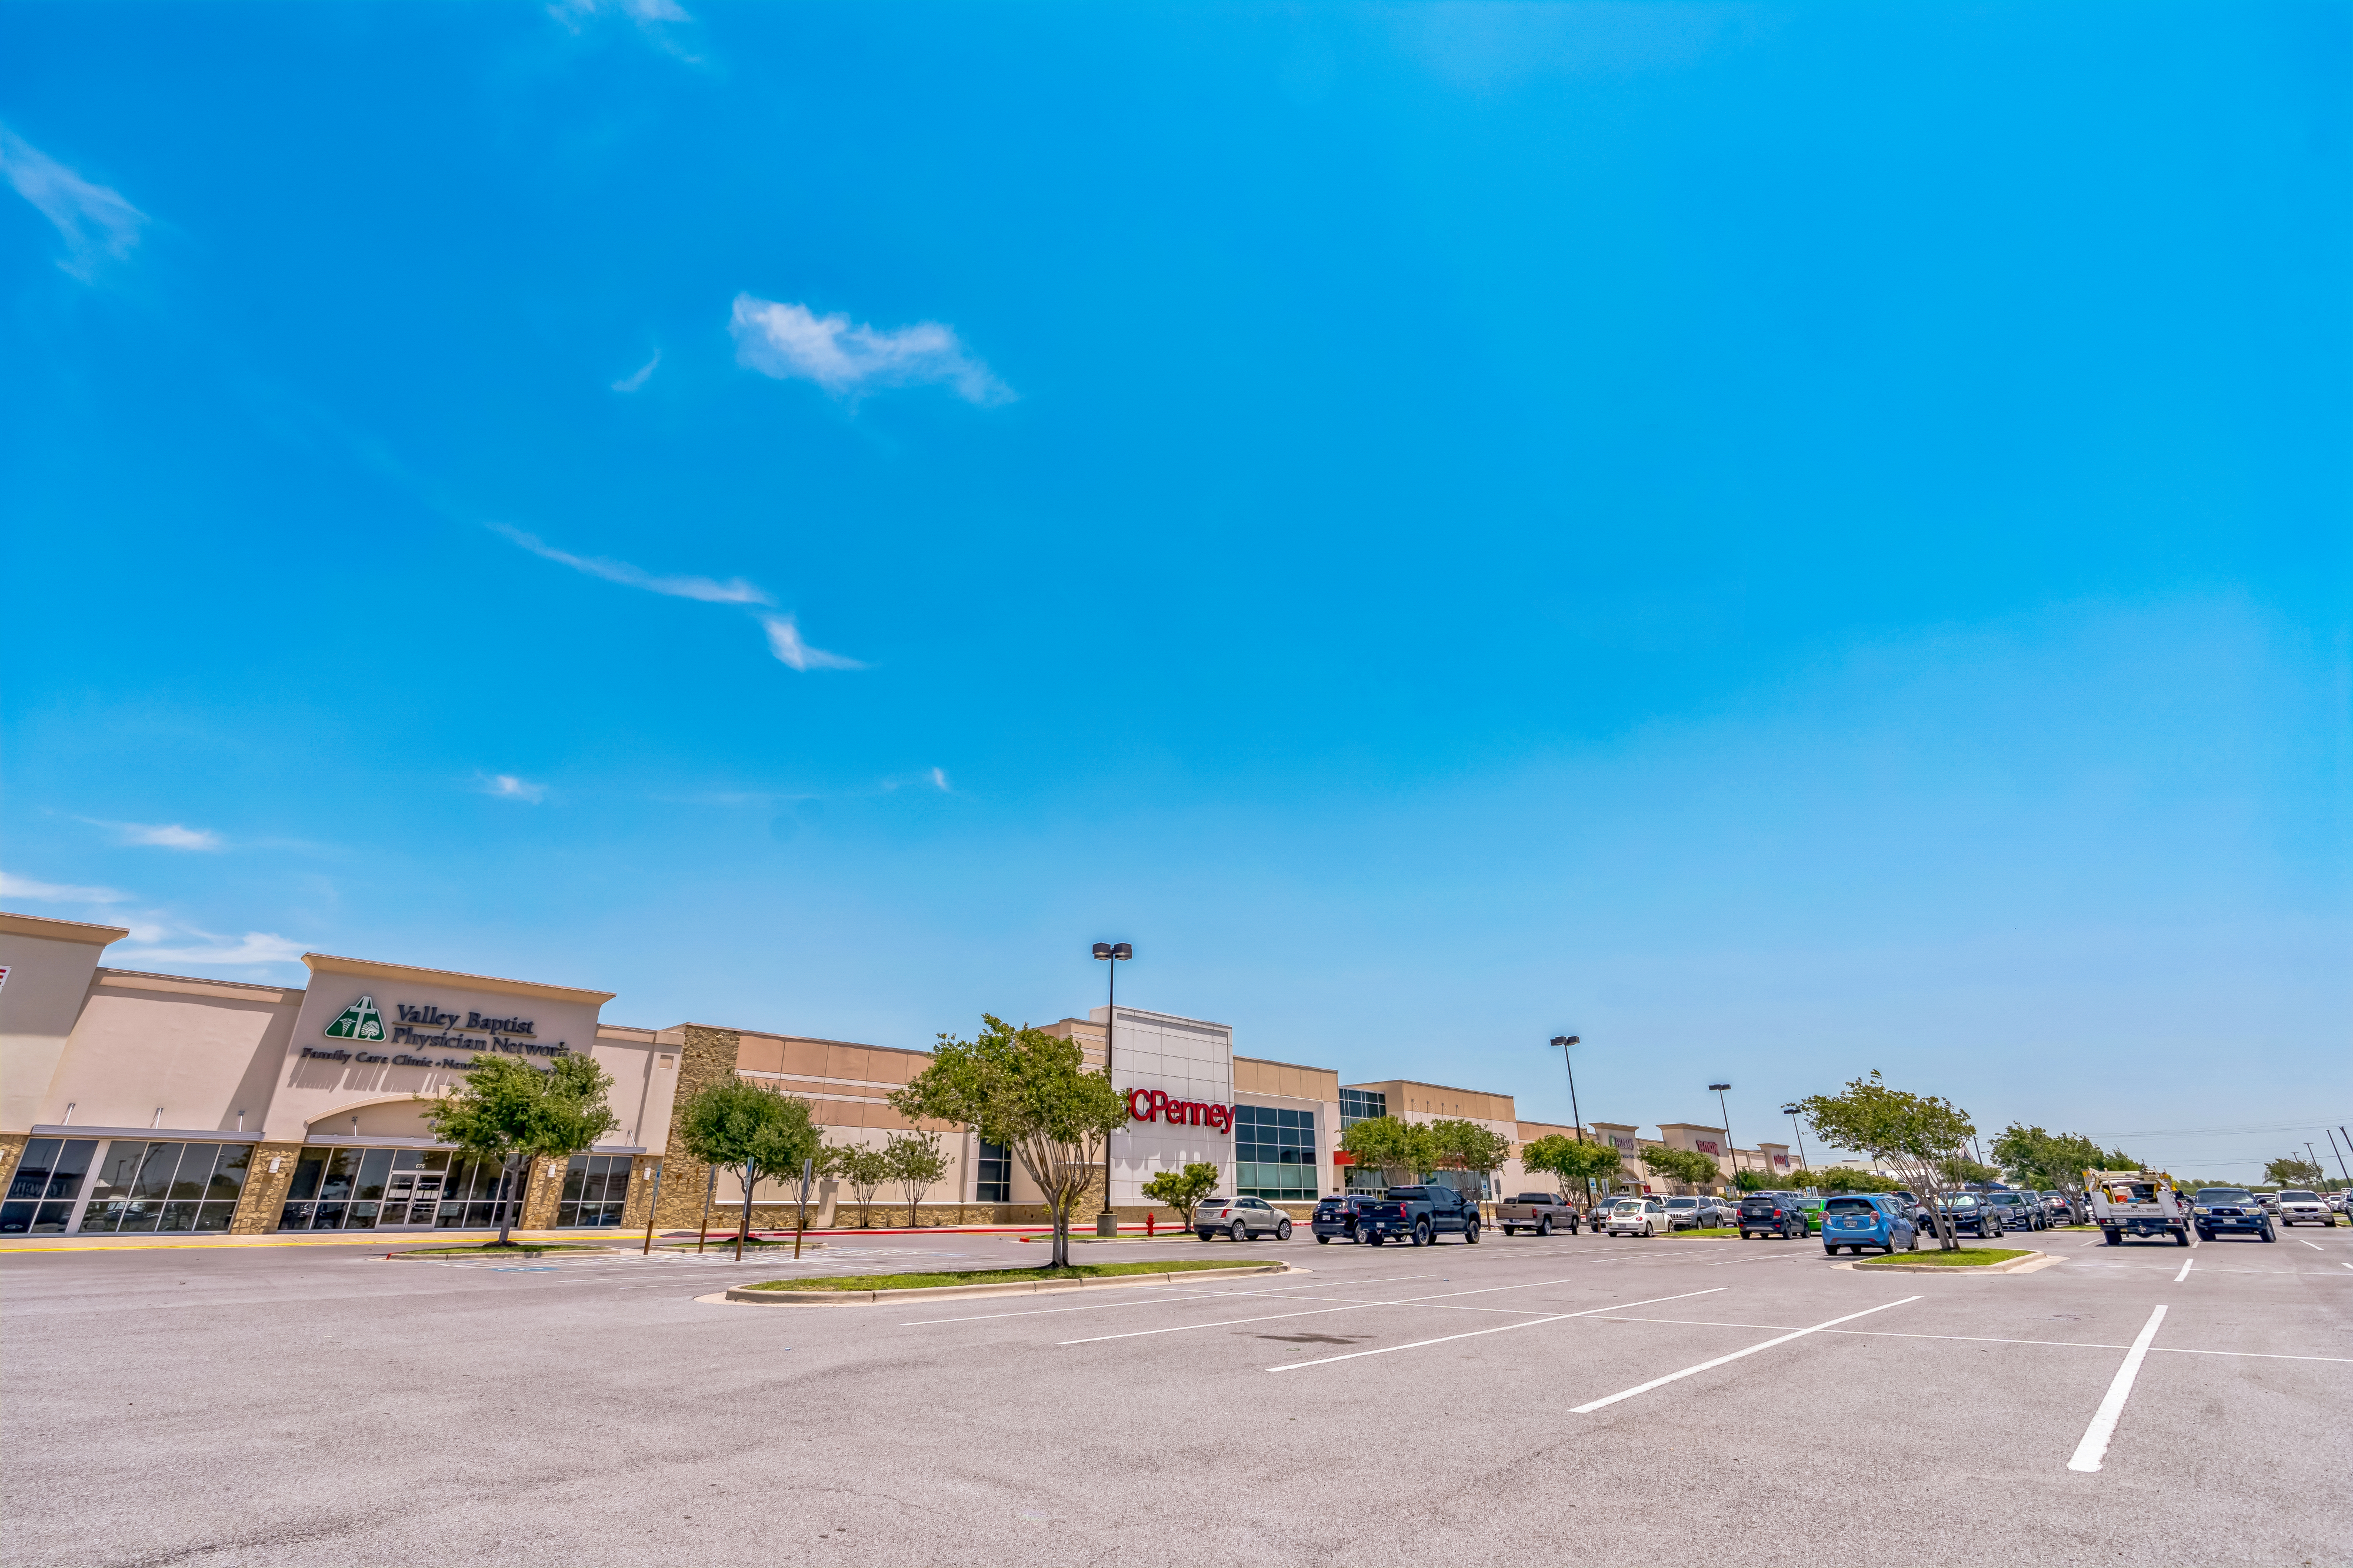
McAllen, TX · Retail
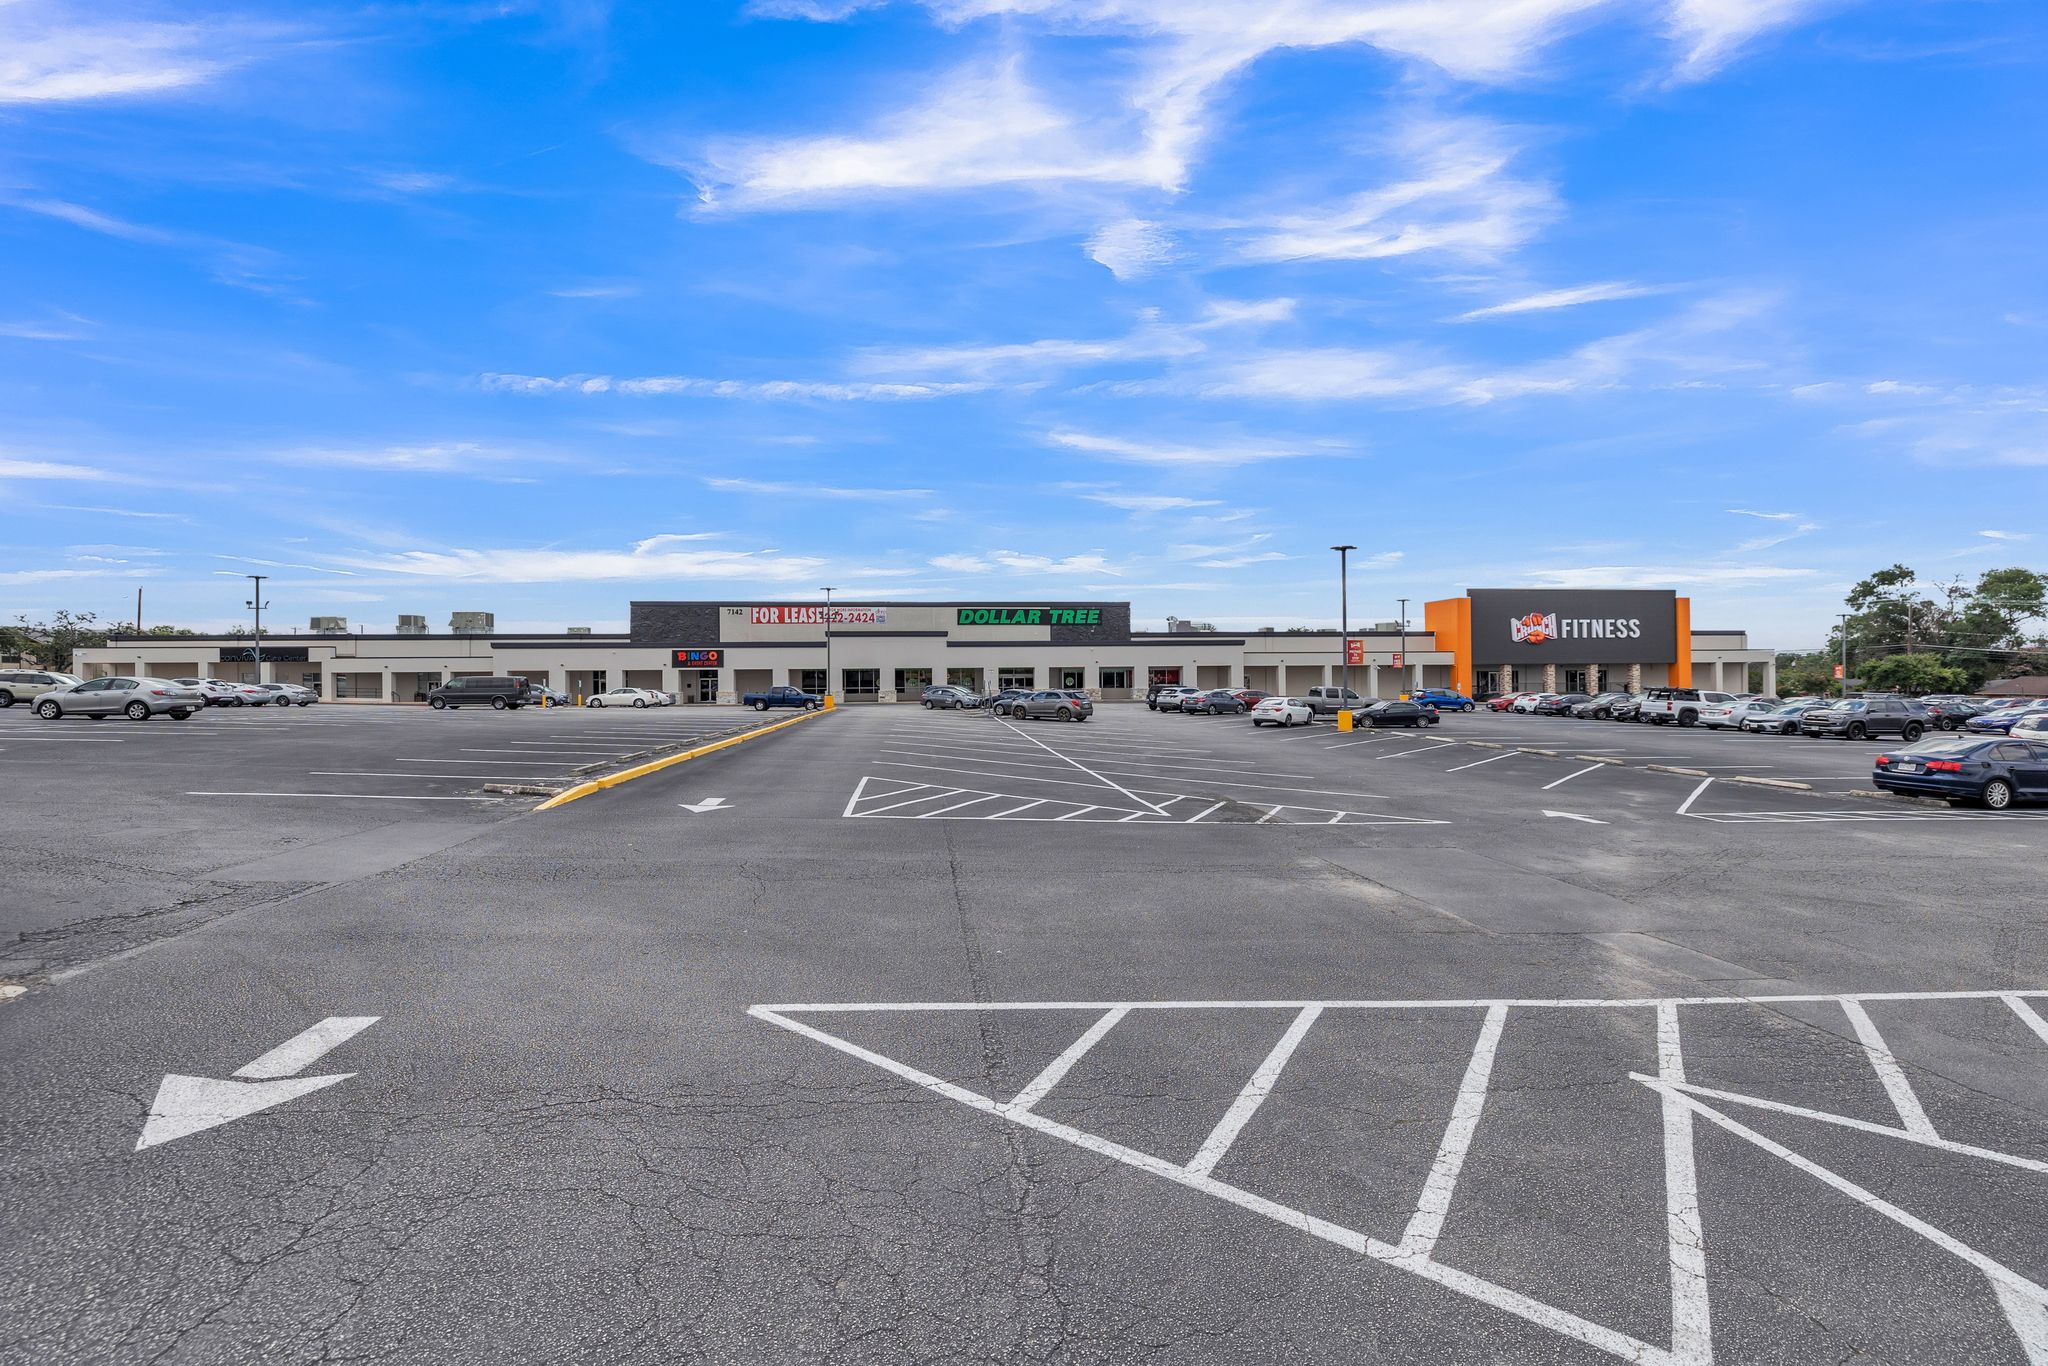
San Antonio, TX · Retail
Property Ownership & Management: Each real estate investment opportunity is sponsored through a separate special-purpose entity (SPE, LLC, or LP). The applicable Investment Entity, and not OTIMA Investments LLC or its principals in their individual capacities, acquires, owns, finances, operates, and disposes of the respective property. OTIMA or its affiliates may serve as manager, sponsor, or service provider as governed solely by the relevant Offering Documents.Read ownership disclosure →